Shortage of widebody aircraft is putting air cargo under increasing pressure

Intercontinental air freight capacity will remain tight for at least the next five years. As long as demand remains stable, freight rates are therefore likely to stay high and airlines are set to continue posting solid profits. For companies looking to grow, however, there is a drawback: those that receive no or only a few new aircraft in the coming years will only be able to expand through acquisitions or vertical integration.
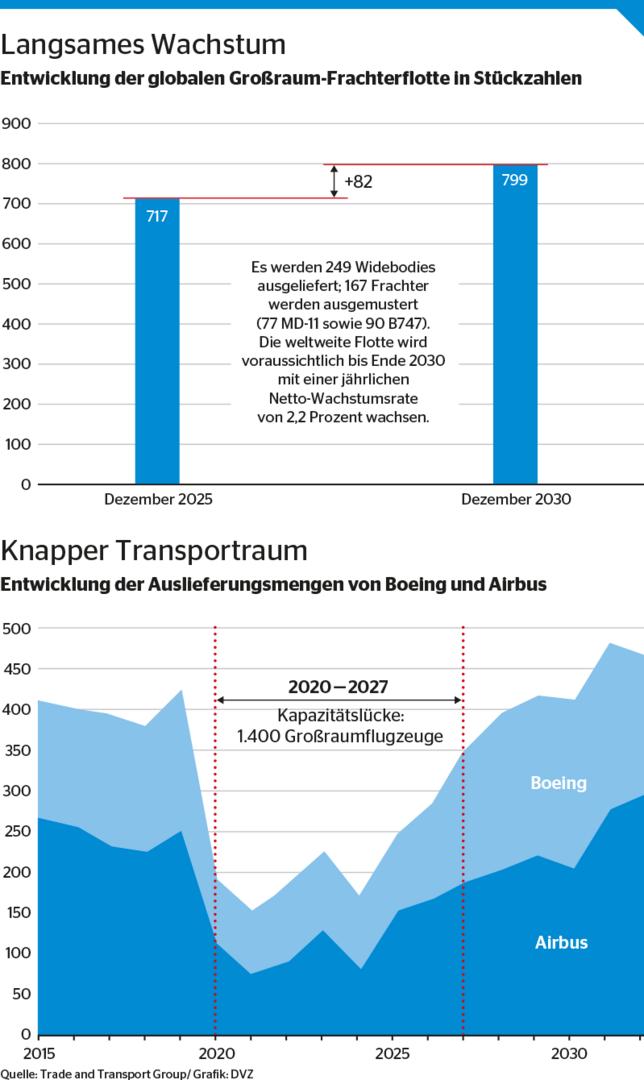
In recent years, manufacturers delivered too few passenger and cargo aircraft. Wide-body passenger aircraft are particularly important for the air freight industry because, normally, around half of the volume is transported not on dedicated cargo aircraft but as a by-product of passenger transport. Between 2020 and 2027, there is therefore likely to be a “shortfall” of around 1,400 aircraft – roughly 23 per cent of the global wide-body fleet currently in service.
Airbus and Boeing are facing problems
Since 2019, the fleet has grown by an average of only around 1 per cent per year. So far, the industry has only been able to cope by taking older aircraft out of service later than planned. As a result, the average age has risen from 10.9 to 13.2 years over the past six years.
This is primarily due to production problems at the aircraft manufacturers Airbus and Boeing. Since 2020, deliveries have been less than half the previous rate of around 400 wide-body aircraft per year. Certification and delivery of cargo aircraft have also been significantly delayed: the 777 conversion programmes are, in some cases, years behind schedule, and the entry into service of both the A350F and the 777-8F has been postponed several times.
Analysts do not expect normal delivery rates for passenger aircraft before 2027. If the certification of the 777-9 suffers further delays or if new production problems emerge, this date could slip even later. For cargo aircraft, the bottlenecks are likely to persist for even longer – at least until 2030.
For intercontinental services, the 747, 777, and, soon, the A350 freighters are particularly relevant. Smaller models such as the 767 or A330 tend to be used on regional routes because they cannot compete with the larger models in terms of unit costs. Admittedly, the B767 and A330 have recently been seen increasingly on intercontinental routes due to high market rates. However, they remain a marginal phenomenon there and are likely to disappear again in the long term.
In this market environment, the global freighter fleet is expected to grow by a maximum of around 2.1 per cent per year – actual growth could be even lower. This is because ICAO emissions regulations permit production of the 777-200F only until 31 December 2027, whilst the new Airbus A350F and the Boeing 777-8F are not expected to be delivered until 2027 and 2029, respectively. More 777 conversions would be theoretically possible, but are effectively limited by the continuing strong demand for passenger aircraft.
This supply shortage is occurring in a market whose growth dynamics have fundamentally changed. Until 2008, international trade in goods grew by just under 7 per cent per year; since then, growth has slowed to below 3 per cent. The situation was similar for air freight: its annual growth rate stood at just under 7 per cent until around 2005 and gradually fell to between 2 and 3 per cent in the following years.
The causes are structural in nature. Until around 2015, the picture was characterised by an increasing geographical expansion of supply networks and the trend towards far-shoring. Since then, analysts have observed an increasing regionalisation of global investment flows – driven both by geopolitical developments and by policy measures aimed at strengthening domestic supply chains. While these trends have not brought trade to a standstill, they have certainly significantly dampened its growth.
Against this backdrop, the structure of the air freight business has undergone a fundamental transformation over the past ten years. As recently as 2015, around 80 per cent of traffic consisted of freight, 17 per cent of express parcels, and 3 per cent of postal items.
Particularly since 2018/2019, the number of cross-border e-commerce shipments – especially from China – has risen sharply. Today, less than two-thirds of air freight volume comes from the traditional freight forwarding business, whilst 18 per cent each comes from express shipments and e-commerce. Postally, this traffic is no longer commercially relevant on a global scale.
E-commerce is faltering
Between 2015 and 2025, the international air freight market grew by an average of around 2.7 per cent annually in terms of tonnage handled. In its recently published Commercial Market Outlook, Boeing forecasts long-term growth of 3.7 per cent per year, whilst Airbus had projected 3.3 per cent just a year ago. Over the next five to six years, growth rates are likely to range between 2.8 and 4.8 per cent. The higher rate depends largely on whether demand for parcels via providers such as Temu, Shein, or AliExpress continues to rise.
However, this sector has been in crisis since at least the abolition of the 800 dollars customs and tax exemption threshold in the US on 1 May 2025. In the twelve months that followed, there was a massive slump in business, which stronger growth in Europe only partially offset.
However, the European e-commerce market has also been contracting since December 2025, and the decline has already been significantly exacerbated by the 3 euros EU import levy introduced at the beginning of July.
However, a decline in direct goods shipments from China to the end consumer does not spell the end of the market. In future, demand is likely to be met primarily from localised stock, which could also lead to a shift in certain flows from air freight to sea freight. In the US, e-commerce traffic has already shrunk from around 110,000 to 35,000 tonnes per month – yet at the same time, there has been an increase in the volume of consolidated textile shipments by air freight.
At the same time, the geography of trade flows has also shifted. Between 2005 and 2015, China’s share of global imports rose from around 12 per cent to 20 per cent (excluding energy, raw materials, and other bulk goods). By the end of 2025, this share stood at 21 per cent. China’s share of US imports initially rose to just under 25 per cent by 2010, but remained at that level until around 2021, standing at 20 per cent by the end of 2024 and as low as 15 per cent by the end of 2025. China’s share of EU imports shows a moderate long-term upward trend, standing at 6 per cent in 2005 and 12 per cent in 2022. Since then, the share has fallen slightly and stood at just under 10 per cent at the end of 2025. Developments have also varied across the sectors relevant to air freight, although China’s importance has increased significantly almost everywhere.
The AI boom arrives at a crucial moment.
Overall, however, the air freight market in the US has not suffered a noticeable slump, as the shortfall in e-commerce traffic has been offset by AI-driven investment in servers, RAM, and other hardware. A similar trend is not evident in Europe, primarily because investment in data centres there is not currently at the same level.
Investment in data centres, driven largely by the AI boom, totalled around 400 billion US dollars in 2025 and is expected to be 75 per cent higher in 2026. The scale of this growth is illustrated by the associated energy consumption: according to the Energy Information Administration, electricity consumption attributable to data centres has already doubled from around 250 terawatt-hours in 2019 to 500 terawatt-hours in 2025.
Analysts expect it to double again by 2030 and reach 1,200 terawatt-hours by 2035. If the AI boom proves to be a bubble, this would certainly affect the overall volume – but a complete collapse of the market is rather unlikely given the already limited air freight capacity.
Who is likely to grow – and who isn’t
Based on the current order book, airlines such as Emirates, FedEx, China Cargo Airlines, and Cathay are well placed to expand their cargo operations over the next three years.
On the passenger side, around 44 per cent of the backlog of wide-body aircraft due for delivery is accounted for by just ten airlines – including the Gulf carriers Emirates, Riyadh Air, Qatar Airways, and Turkish; Asia-based airlines such as JAL, China Airlines, and Korean Air; as well as United, Delta, and Lufthansa. Although many of the orders placed by the latter three are intended to replace ageing fleets, they nevertheless provide a good starting point for expanding belly cargo capacity.
All other airlines must either wait or rely on acquisitions or a vertical expansion of their business. Lufthansa has already set an example with its takeover of ITA Airways, and the integration of TAP Air Portugal would have a similar effect. Condor, too, is known to be seeking a strategic investor. Whilst cross-border investments are more difficult to achieve due to national ownership regulations – even if full integration is not possible, pooling shared capacity at least remains an option.
Some airlines have instead attempted vertical expansion – for example, Emirates with its “Courier” product, due to be launched in 2025, or Lufthansa, which recently consolidated its e-commerce logistics and customs clearance expertise under Globecross GmbH. However, such projects have so far rarely had a significant impact on overall turnover. (ol)
Frederic Horst is the founder and managing director of Trade and Transport Group, a consultancy specialising in air freight.